UK Property Transactions Are Falling… But What Are the Numbers Actually Telling Us?
Property headlines have an interesting habit.
When prices rise:
"Property market booming."
When transactions fall:
"Property market struggling."
When mortgage rates increase:
"Buyers retreat."
And when they fall:
"Confidence returns."
For landlords and property investors, reacting to every headline would be exhausting.
So instead of asking whether the latest figures are good or bad, perhaps there's a better question:
What are the numbers actually telling us?
The latest UK property transaction figures provide a good example.
UK transactions fell in August
HMRC estimates that 95,220 residential property transactions completed in August 2026 on a seasonally adjusted basis.
That's:
1% lower than July 2026
and
2% lower than August 2025.
The unadjusted figure was 96,250 transactions; down 11% from July and 9% compared with August last year. These figures cover UK residential transactions worth £40,000 or more. GOV.UK
At first glance, the conclusion seems obvious.
The property market is slowing.
But property data rarely tells its whole story in one number.
Zoom out and the picture changes
Look beyond August alone and something interesting happens.
The figures show 486,950 unadjusted residential transactions between April and August 2026, compared with 442,790 during the corresponding period a year earlier.
So while August itself was weaker year-on-year, activity over that broader five-month period was higher.
That's why individual monthly statistics need context.
One weak month doesn't automatically establish a collapsing market.
Equally, a stronger five-month period doesn't guarantee the next five months will remain strong.
Markets move.
And different indicators tell us different things.
There's another problem: these transactions aren't really about August
This is probably the most important part of the story.
- HMRC records transactions when they complete.
- But buying a property takes time.
- The offer may have been accepted months earlier.
- The mortgage may have been agreed under different conditions.
- Interest rates may have changed.
- Buyer confidence may have changed.
- The economic outlook may have changed.
So August completion figures shouldn't simply be interpreted as:
"This is what buyers think about property today."
They're partly telling us what was happening further back in the transaction pipeline.
That's why property investors need to understand not just the number, but what the number measures.
Look forward as well as backwards
For a more current indication of financing activity, mortgage approvals are useful.
And those numbers are softer.
Bank of England data show net mortgage approvals for house purchases fell from 55,900 in July to 54,900 in August.
That's also below the previous six-month average of around 60,100.
At the same time, the effective interest rate on newly drawn mortgages increased from 4.45% to 4.60%. Bank of England
That gives us another piece of the puzzle.
Borrowing has become more expensive and fewer purchase mortgages are being approved.
But even that shouldn't be turned into:
"Don't buy property."
Or:
"Now is the perfect time to buy."
Neither conclusion can be drawn from these statistics alone.
A slower market isn't automatically a bad market
This is where things become more interesting for landlords and investors.
Different markets create different conditions.
In a rapidly rising market, buyers may face:
- More competition.
- Less negotiating power.
- Pressure to make decisions quickly.
- Properties selling before they've been properly assessed.
In a slower market, there may be:
- More choice.
- More time to investigate.
- Greater willingness from some sellers to negotiate.
But potentially higher financing costs and weaker short-term price momentum.
Neither environment automatically produces a good investment.
The individual deal still has to work.
Property investors should know their own numbers
This is the part I think gets lost whenever national property statistics are published.
Suppose UK transactions fall another 10%.
What does that actually tell you about a particular three-bedroom property in Leeds, Manchester, Birmingham or London?
Not enough to make the decision.
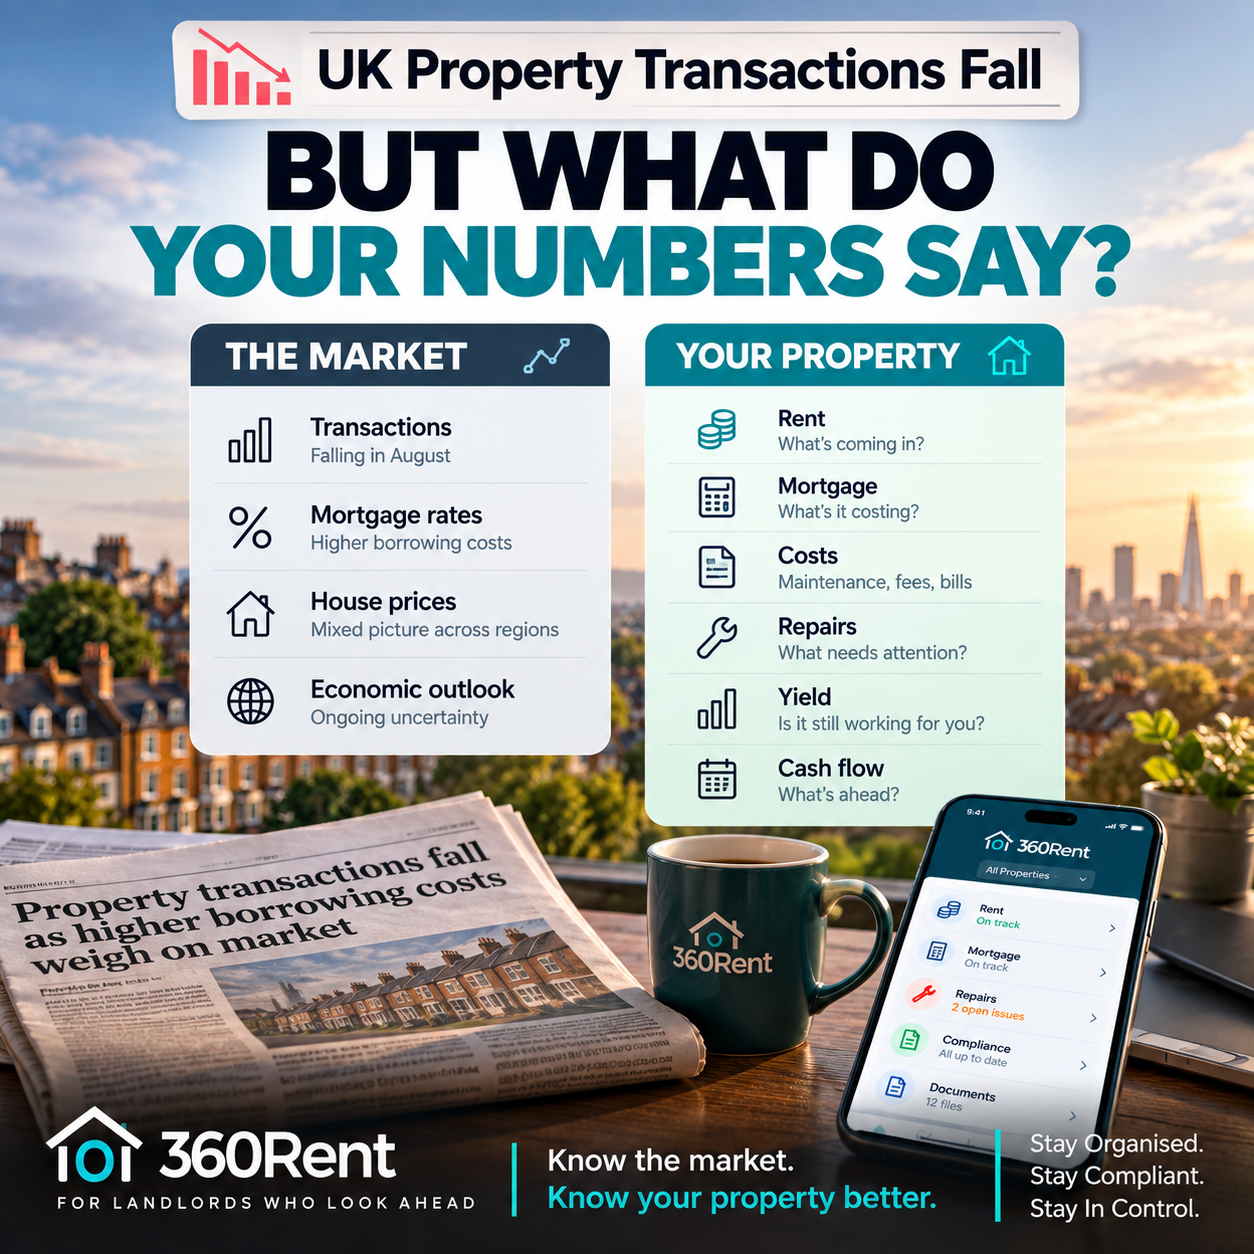
For an individual landlord, the more relevant questions might be:
- What's the purchase price?
- What's the realistic rent?
- What's the mortgage cost?
- What's the expected maintenance?
- What are the management costs?
- What's the likely void allowance?
- What compliance work is required?
- What's the local rental demand?
- What happens if interest rates remain higher for longer?
A national statistic can provide context.
It cannot do the deal analysis for you.
Headlines describe markets. Numbers help you make decisions.
There's a distinction worth making.
Property news is useful.
It tells us about the environment we're operating in.
But professional property decisions require another layer.
Data.
And not just national data.
Your data.
A landlord should increasingly know what each property is doing.
- Rent.
- Costs.
- Repairs.
- Compliance.
- Tenancy information.
- Mortgage commitments.
- Important dates.
- Documents.
The better organised that information becomes, the easier it becomes to distinguish between what is happening to the property market and what is happening to your property business.
Those aren't always the same thing.
This matters even more when conditions become difficult
When property prices are rising quickly and borrowing is cheap, inefficiency can sometimes hide.
- A forgotten expense doesn't feel significant.
- An inefficient management process can be tolerated.
- A mediocre investment may be rescued by capital growth.
- When margins become tighter, those weaknesses become more visible.
- An extra £100 matters.
- A prolonged void matters.
- An unexpected repair matters.
- A higher mortgage payment matters.
- Management costs matter.
That's why difficult markets don't necessarily mean landlords need to panic.
They mean landlords need to understand their position.
Uncertainty makes information more valuable.
Don't try to predict everything
Nobody knows exactly what the UK property market will look like twelve months from now.
- Interest rates can change.
- Government policy can change.
- Economic conditions can change.
- Local markets can behave very differently from national averages.
- Trying to perfectly predict all of it isn't realistic.
- But landlords can control something else.
- They can know their properties.
- They can understand their costs.
- They can maintain good records.
- They can monitor important dates.
- They can assess opportunities properly.
And they can make decisions from information rather than headlines.
That's part of what we're trying to build with 360Rent
360Rent isn't designed to tell landlords whether property prices will rise or fall.
It's designed around something much more controllable:
Helping landlords understand and manage the properties they already own.
Keep important property information together.
- Track compliance.
- Record repairs.
- Organise tenancy information.
- See what's coming up.
- Reduce the amount you have to remember.
Because there will always be another headline.
- Another interest-rate decision.
- Another Budget.
- Another prediction about property.
- Another statistic.
Landlords can't control those things.
They can control how well they run their property business.
And sometimes that's the most valuable information of all.
Stay Organised. Stay Compliant. Stay In Control.
This article is general information and does not constitute financial or investment advice. Property markets vary significantly by location and individual circumstances.